Blog · Insurance
Insurance claims automation: an AI agent for claim pre-review
· 6 min read
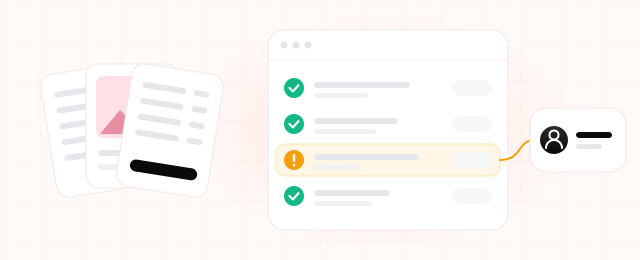
A home insurance claim lands on a Tuesday morning. Water from the flat upstairs has ruined a kitchen ceiling. The policyholder has sent the claim form, photos with a short description and the contractor's invoice; the adjuster's report follows two days later. Then the file waits for someone to read it all against the policy. Three weeks on, someone notices the leak inspection report is missing, the customer gets another call, and payment slips again. Insurance claims automation can close this gap by doing the first read on the day the file opens.
What does a claims pre-review agent check?
An agent reads every document in the file, pulls out the facts that matter (policy number, date of loss, type of damage, amount claimed, invoice lines, the adjuster's findings) and holds them up against the policy.
- Was the policy in force? The date of loss has to fall inside the policy period.
- Is the peril covered? The reported damage should match a listed cover.
- Is the amount within the limit? Sum insured, any sub-limit in the special terms, and the deductible.
- Is anything missing? The file is compared with your document list for that line of business.
- Do the documents agree? Dates on the form and in the adjuster's report should match, and so should the invoice address and the insured property.
Each finding is logged with its source, then the file goes to the adjuster. The agent never approves payments, sends rejections or closes files.
Walking through one file
Here is the water damage claim from the opening. The figures are illustrative.
- Reads the documents: claim form, the description sent with the photos, a contractor invoice for 48,500 TRY, and the adjuster's report.
- Opens the policy: home policy, active. Date of loss 14 March 2026, policy period 1 January to 31 December 2026. Fine.
- Checks cover: water damage is covered. Fine.
- Checks the limit: special term 3 caps this cover at 40,000 TRY. The claim is 8,500 TRY over. Flag: over limit, source special term 3.
- Checks the document list: your list for this line asks for a leak inspection report. There isn't one. Flag: missing document.
- Hands over: the adjuster sees a short summary with two flags, plus a draft message asking the customer for the missing report. Your team decides whether to send it.
Nowhere does it say "pay 40,000". Which invoice lines belong to this loss, how the deductible applies and what gets paid remain the adjuster's call. The adjuster sees both issues in the first minute instead of finding them on page twelve.
Where the agent stops
- Coverage and payment. The adjuster and claims handler decide both. The agent hands over a completed checklist, not a recommendation.
- Suspected fraud. Dates that don't line up or documents that contradict each other get flagged. Treating a file as suspicious, and acting on it, needs an experienced person; plenty of inconsistencies turn out to be typos.
- Telling a customer no. A conversation about a rejected or partly paid claim decides whether that customer renews. Keep it human.
Is AI claims processing a good fit for your team?
It pays off where similar files arrive often and get the same manual checks, for example at:
- agencies and brokers opening dozens of motor or home claims every month
- claims teams collecting documents from email, WhatsApp and a portal at once
- teams where files go back to the customer two or three times for missing paperwork
With a few claims a month, setting up an agent is more work than doing the checks yourself. Large commercial or engineering risks, where every file is different, gain little too: there the expert assessment is the job.
An email agent can sort incoming documents into the right claim, and a customer service agent can chase customers for paperwork over WhatsApp.
Run the numbers for your own team
Hours saved per month = claims per month × minutes of document checking per claim × share the agent takes over ÷ 60
Example figures: 250 claims a month, 20 minutes of checking each, and an assumed 60% of that handled by the agent. 250 × 20 × 0.6 ÷ 60 = 50 hours a month.
The share is never 100%, since a person reviews every flag. The formula also leaves out the waiting time saved when a missing document is spotted on day one instead of week three. Measure that in your own files as days from first notice to payment.
Before you switch it on
- Write down the document list. Required documents per line of business belong in a written list, not in your team's heads. That list is what the agent works from.
- Give it access to policy data. The agent needs your policy system, or at least the policy PDFs. Test early whether free-text special terms are read correctly.
- Plan for data protection. Claim files are full of personal data. In health or personal accident lines they can hold health data, a special category under both GDPR and Turkey's KVKK. Know where data is processed and stored and who can see it, and take open questions to your legal adviser.
- Keep a record of every flag. Each flag should say why it was raised, citing the document and the policy clause. That helps the adjuster now and answers questions if the file is reviewed later.
- Limit what it can touch. Decide which fields the agent can read and which it can write. Claim status changes and payment screens stay out of reach.
Start with one line of business
Pick the line where you open the most files; for many agencies that is motor or home. For the first weeks, compare the agent's flags with the adjuster's own review. What did it catch, what did it miss, what did it flag for no reason? That comparison sharpens your document lists and rules. Once results are steady, add the second line.
A sample policy check is shown among our solutions.
Let's set up pre-review for your claim files
In a short discovery call we'll look at which line of business to start with and which checks in your files the agent can take over.